How Credit Scores Work: The 5 Factors That Matter Most
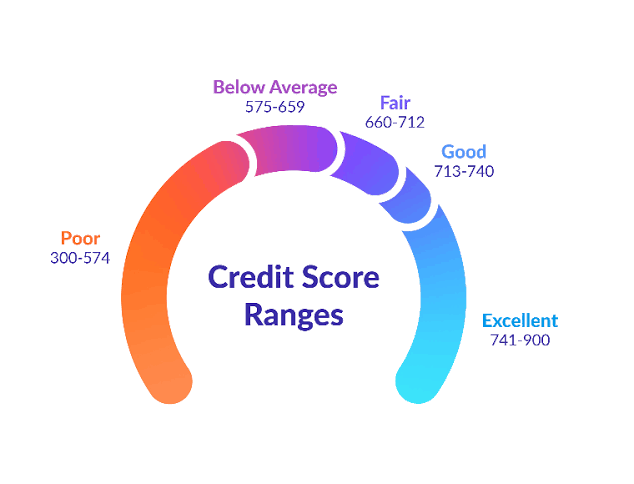
Your credit score is built from five factors: payment history, amounts owed, length of history, new credit, and credit mix. Here is how each one works and how to improve your score.
 Arkam
Your credit score is built from five factors: payment history, amounts owed, length of history, new credit, and credit mix. Here is how each one works and how to improve your score.
A home equity loan gives you a fixed lump sum, while a HELOC works like a flexible credit line. Here is how each one works, what they cost, and which suits your needs.
You don’t need thousands of dollars to start investing. Here is how to begin with small amounts using fractional shares, index funds, robo-advisors, and a simple step-by-step plan.
Change default passwords, use WPA3, update firmware, set up a guest network, and disable risky features. A practical, step-by-step guide to securing your home Wi-Fi.
From the new RAP and Tiered Standard plans to PSLF, the avalanche method, and refinancing, here are the student loan repayment strategies that work in 2026.
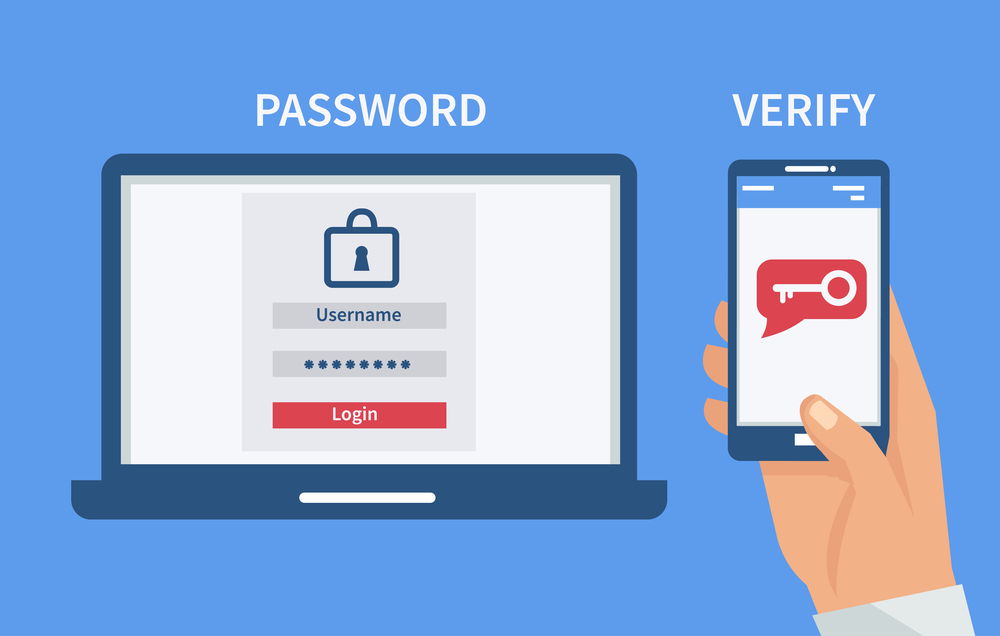
Not all two-factor authentication is equal. Here are the common 2FA methods ranked from weakest to strongest, from email and SMS codes to passkeys and hardware security keys.
Phishing scams arrive by email, text, phone, QR code, and social media. Here are the 10 warning signs, real-world examples, and exactly what to do if you’ve already clicked.
Term life insurance is cheap and simple. Whole life lasts forever and builds cash value, but costs far more. Here is how the two compare and how to decide which one fits your family.
Rules of thumb like “10 times your income” are a start, but a needs-based calculation gives a much more accurate number. Here is a step-by-step method with a worked example.
Premiums, deductibles, copays, coinsurance, and out-of-pocket maximums all affect what you really pay for health care. Here is what each term means, with a clear example.